Amazon Earnings Preview: AWS Backlog Meets $220B Capex

Amazon Earnings Preview: AWS Backlog Meets $220B Capex
By:Mike Butler
Amazon Earnings Preview: Can AWS Growth Justify $220 Billion in Spending?
By: Mike Butler
- Amazon reports Q3 2026 earnings after the close on Thursday, October 29, with analysts expecting EPS of $1.96 on revenue of roughly $202.2 billion, up about 12% year over year and right at the top of the company’s $197 billion to $202 billion guidance range.
- AWS is the main event. Revenue grew 37% to $42.2 billion in Q2, the fastest pace in 18 quarters, and the backlog jumped from $364 billion to $496 billion in a single quarter.
- Amazon raised its 2026 capital expenditure outlook to roughly $220 billion in July, up from $200 billion, partly due to higher memory prices. Trailing twelve month free cash flow has turned negative at $7.6 billion.
- Options are pricing in a move of about 7.7% in either direction, in line with Amazon’s 10-year average earnings move, but the stock has exceeded its implied move in 12 of its last 17 reports.
- The key question for the print is whether AWS acceleration and a sold-out capacity story can outweigh growing concern about how much the AI buildout is costing.
Amazon Earnings Preview - October 2026
Amazon (NASDAQ: AMZN) enters its Q3 report in an unusual spot: strong fundamentals, but a stock that has been stuck. Shares are up roughly 8% year to date and trade around $262, well below the 52-week high of $287.20 set in early August. That peak came right after the Q2 report, when the stock surged 15.3% in a single session on the AWS acceleration. Since then, a broader pullback in AI-linked names and rising oil prices have taken some of the air out of the rally, and investors have grown more sensitive to hyperscaler spending.
Expectations are modest on the surface. Consensus EPS of $1.96 is only slightly above the $1.95 Amazon posted in Q3 2025, but revision momentum has been positive, with 11 analysts raising estimates over the past 30 days against three cuts. Amazon guided operating income to $22.5 billion to $26.5 billion, compared with $17.4 billion in the year-ago quarter, so profit growth at the operating line is the more meaningful number to watch than headline EPS.
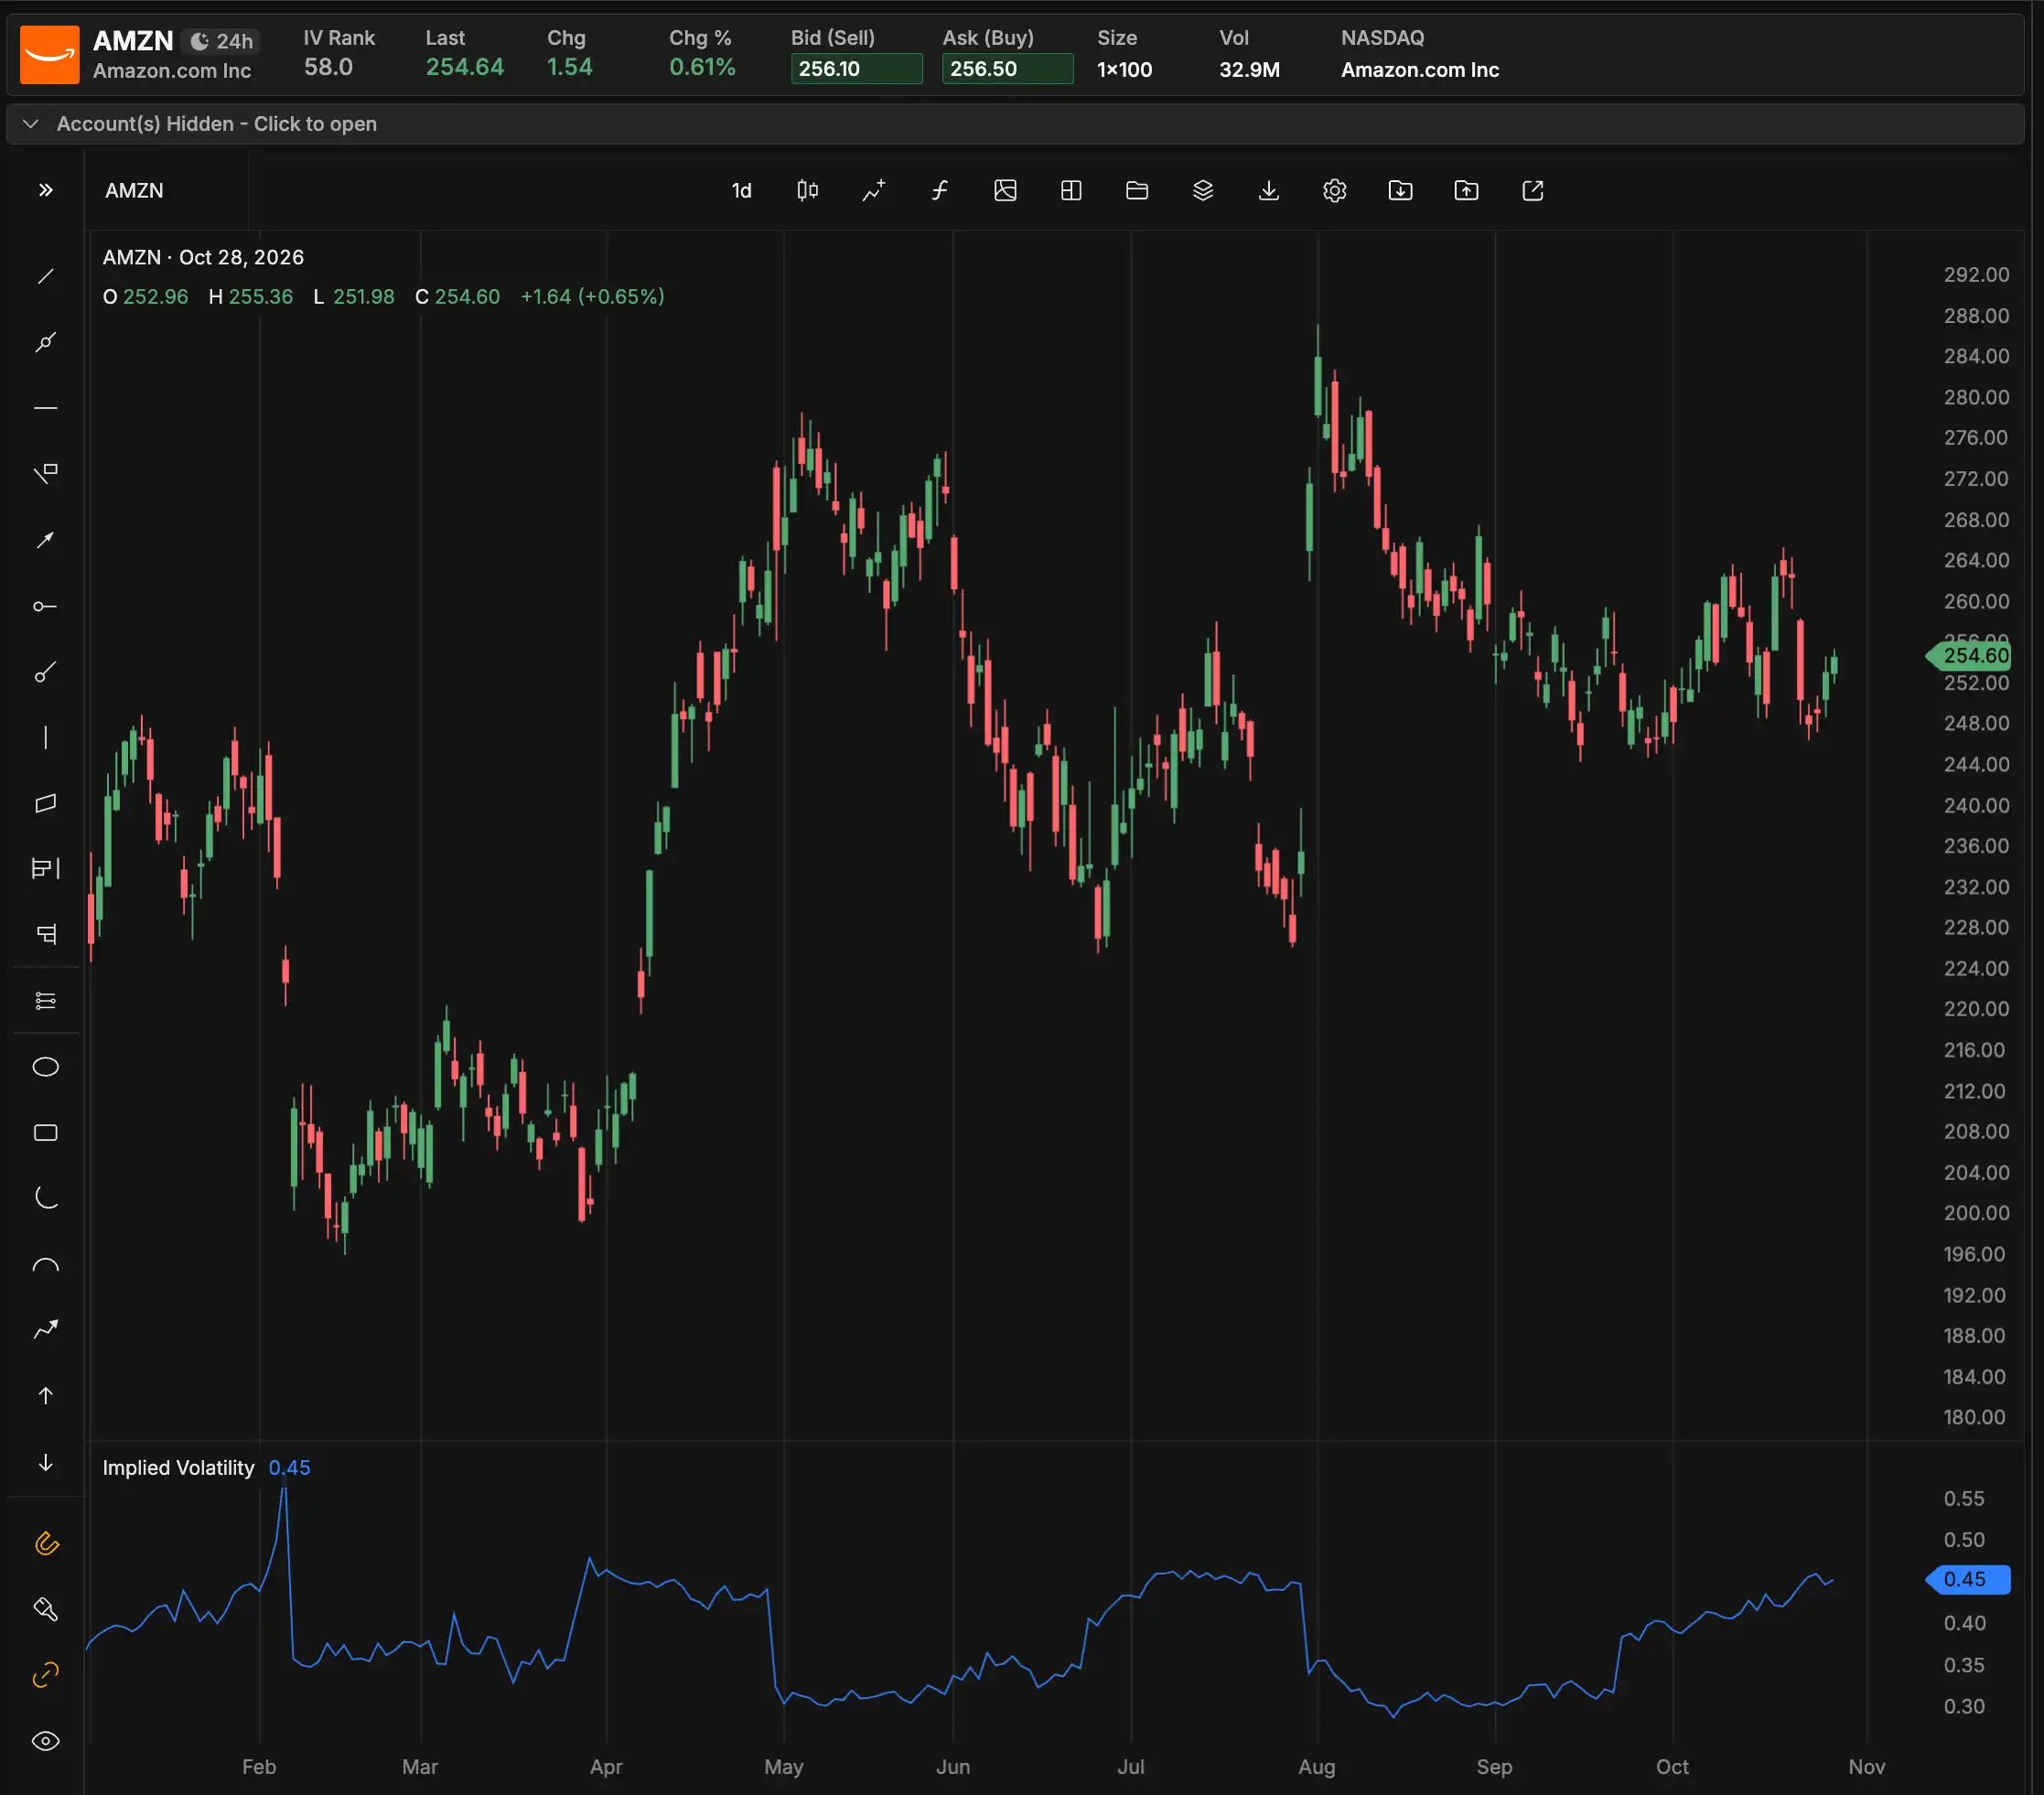
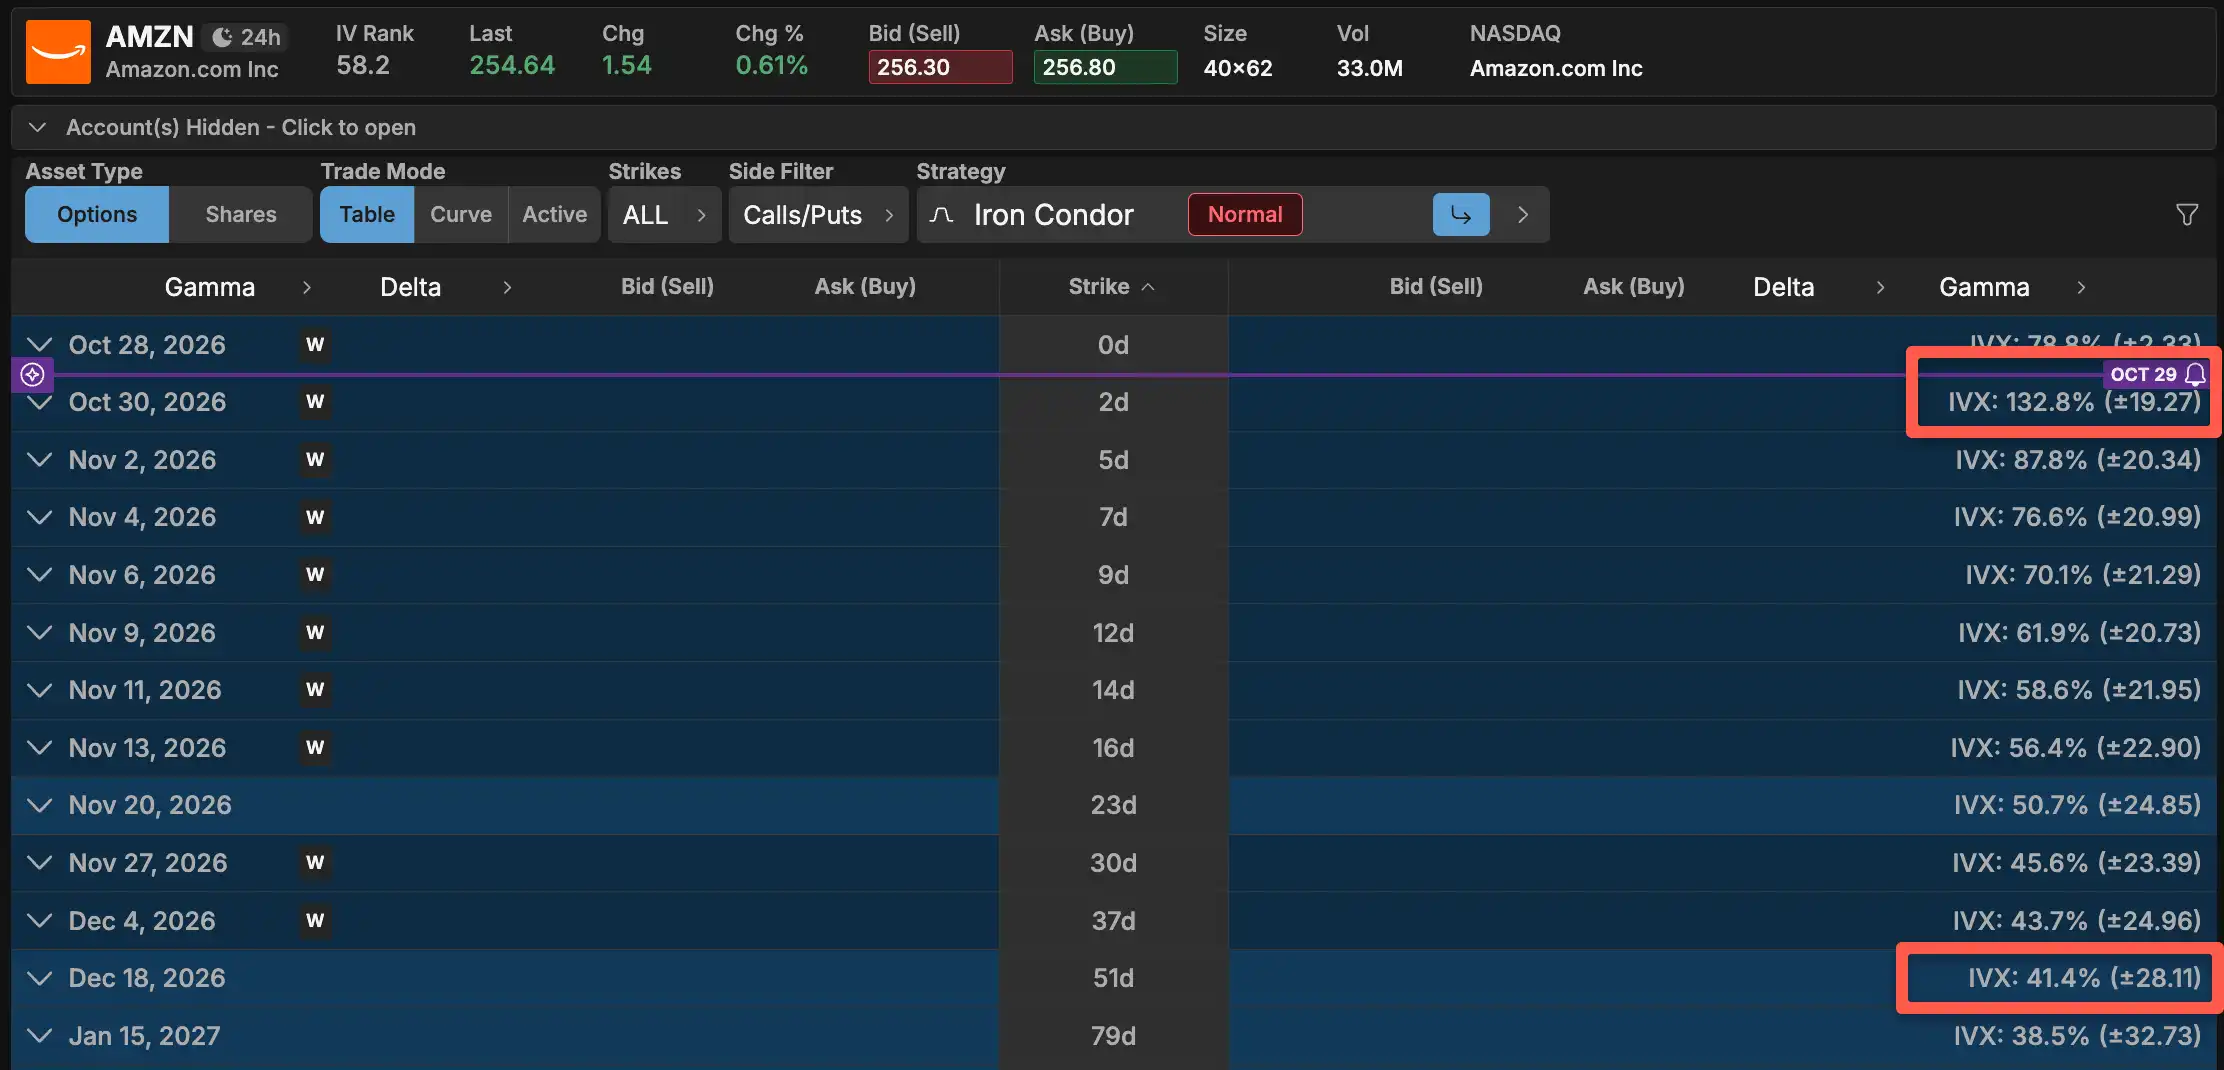
Amazon’s implied volatility is elevated heading into the earnings announcement, with options pricing an expected move of roughly 7.7% in either direction. That lines up with the stock’s 10-year average earnings move, but the recent history is worth noting. The last few reports have produced moves larger than what options priced, which tells you the market has struggled to settle on how to value Amazon’s AI investments. With the stock near $262, a 7.7% move puts the post-earnings range roughly between $242 and $282. Unlike MSFT and GOOGL earnings previews we wrote about, AMZN stock has a much higher ratio of expected move in the weekly cycle compared to December 2026 - the weekly expected move of +-$19 accounts for 67% of the implied range for December, which has just a +-$28 implied range. This means the market is placing a large weight on this earnings announcement and we could see some real fireworks on Thursday, October 29th.
AWS Growth and a $496 Billion Backlog
AWS is where the bullish story lives. Revenue hit $42.2 billion in Q2, up 37% year over year, with a segment operating margin near 39%. Analysts are looking for roughly $45.6 billion in Q3 revenue, with growth estimates ranging from the low 30s to as high as 40% from Bank of America. CEO Andy Jassy said on October 23 that AWS capacity is sold out for 2026, largely sold out for 2027, and that a substantial portion of 2028 is already committed.
The backlog is the cleanest read on demand. It reached $496 billion in Q2, up $132 billion from the prior quarter, supported by multi-gigawatt Trainium commitments from Anthropic and OpenAI. Amazon also said its AI and custom chip businesses have each passed a $25 billion annual run rate. In other words, the constraint is no longer customers, it is how fast Amazon can build and power new capacity.
Amazon’s $220 Billion Capex Question
The other side of that demand is the bill. Amazon raised its 2026 cash capex estimate to roughly $220 billion in July, and Jassy attributed the $20 billion increase to higher memory costs rather than added capacity. That matters because it is the same memory pricing surge that has sent Micron to a $1 trillion market cap, and Amazon is one of the companies paying for it. Spending more than $53 billion in Q2 alone, Amazon has seen trailing free cash flow swing from an $18.2 billion inflow a year ago to a $7.6 billion outflow. Hitting the full-year number implies roughly $61 billion per quarter in the second half, and Morningstar has noted a sixth consecutive raise would not be a surprise. Capex commentary, particularly for 2027, may matter more to the stock than any single line in the income statement.
Retail, Advertising and What Else to Watch
Beyond AWS, the retail side has some noise. Management’s 9% to 12% sales growth guide reflected foreign exchange headwinds and a Prime Day timing shift, and fuel-driven transportation costs and expenses tied to Amazon Leo, the satellite internet project, could weigh on margins. On the other side, advertising is expected to land near $20.9 billion, with third-party seller services around $45.1 billion and subscription services near $13.9 billion. Faster delivery speeds and the Amazon Now expansion are expected to have supported unit growth heading into the holiday quarter, which makes Q4 guidance another key piece of the print.
Bullish Case for Amazon Earnings
The bull case starts with visibility. A $496 billion backlog growing at triple-digit rates, with capacity largely sold out through 2027, gives AWS a revenue runway that few companies can match. If AWS growth holds near or above the 37% posted in Q2 while margins stay near 39%, bulls argue the capex is simply the cost of capturing demand that is already contracted. Morgan Stanley named Amazon its top pick on October 19 with a $350 price target, and the analyst consensus is a Buy with an average target around $335, implying upside of more than 25% from current levels. Valuation is another point in the bulls’ favor, with the stock trading at a forward P/E in the low 20s despite the fastest cloud growth among the hyperscalers. A Q2-style beat on revenue and operating income, paired with commentary that AI margins are tracking in line with the core cloud business, could put the August highs back in play.
Bearish Case for Amazon Earnings
Bears are not doubting demand, they are questioning returns. Free cash flow is negative, capex is heading toward $220 billion, and a meaningful portion of the recent increase went to higher component costs rather than new capacity. The market has also become less forgiving of AI spending in recent weeks, so any hint of a 2027 capex figure well above expectations could outweigh a strong AWS number. Revenue consensus already sits at the high end of guidance, and EPS growth is nearly flat year over year, leaving little room for a stumble in retail margins or Q4 guidance. Competition from Microsoft Azure and Google Cloud remains stiff, and a concentration of backlog among a handful of AI labs adds counterparty risk if funding conditions tighten. With the stock trading well below its August peak and a history of outsized post-earnings moves, a disappointing outlook could send shares sharply lower even on a headline beat.
Mike Butler, tastylive director of market intelligence, has been trading the markets for a decade. He appears on the tastylive morning show Monday - Friday. @tradermikeyb
For live daily programming, market news and commentary, visit tastylive or the YouTube Channel tastylive (for options traders).
Trade with a better broker, open a tastytrade account today. tastylive, Inc. and tastytrade, Inc. are separate but affiliated companies.
Options involve risk and are not suitable for all investors. Please read Characteristics and Risks of Standardized Options before deciding to invest in options.
tastylive content is created, produced, and provided solely by tastylive, Inc. (“tastylive”) and is for informational and educational purposes only. It is not, nor is it intended to be, trading or investment advice or a recommendation that any security, futures contract, digital asset, other product, transaction, or investment strategy is suitable for any person. Trading securities, futures products, and digital assets involve risk and may result in a loss greater than the original amount invested. tastylive, through its content, financial programming or otherwise, does not provide investment or financial advice or make investment recommendations. Investment information provided may not be appropriate for all investors and is provided without respect to individual investor financial sophistication, financial situation, investing time horizon or risk tolerance. tastylive is not in the business of transacting securities trades, nor does it direct client commodity accounts or give commodity trading advice tailored to any particular client’s situation or investment objectives. Supporting documentation for any claims (including claims made on behalf of options programs), comparisons, statistics, or other technical data, if applicable, will be supplied upon request. tastylive is not a licensed financial adviser, registered investment adviser, or a registered broker-dealer. Options, futures, and futures options are not suitable for all investors. Prior to trading securities, options, futures, or futures options, please read the applicable risk disclosures, including, but not limited to, the Characteristics and Risks of Standardized Options Disclosure and the Futures and Exchange-Traded Options Risk Disclosure found on tastytrade.com/disclosures.
tastytrade, Inc. ("tastytrade”) is a registered broker-dealer and member of FINRA, NFA, and SIPC. tastytrade was previously known as tastyworks, Inc. (“tastyworks”). tastytrade offers self-directed brokerage accounts to its customers. tastytrade does not give financial or trading advice, nor does it make investment recommendations. You alone are responsible for making your investment and trading decisions and for evaluating the merits and risks associated with the use of tastytrade’s systems, services or products. tastytrade is a wholly-owned subsidiary of tastylive, Inc.
tastytrade has entered into a Marketing Agreement with tastylive (“Marketing Agent”) whereby tastytrade pays compensation to Marketing Agent to recommend tastytrade’s brokerage services. The existence of this Marketing Agreement should not be deemed as an endorsement or recommendation of Marketing Agent by tastytrade. tastytrade and Marketing Agent are separate entities with their own products and services. tastylive is the parent company of tastytrade.
tastyfx, LLC (“tastyfx”) is a Commodity Futures Trading Commission (“CFTC”) registered Retail Foreign Exchange Dealer (RFED) and Introducing Broker (IB) and Forex Dealer Member (FDM) of the National Futures Association (“NFA”) (NFA ID 0509630). Leveraged trading in foreign currency or off-exchange products on margin carries significant risk and may not be suitable for all investors. We advise you to carefully consider whether trading is appropriate for you based on your personal circumstances as you may lose more than you invest.
tastycrypto is provided solely by tasty Software Solutions, LLC. tasty Software Solutions, LLC is a separate but affiliate company of tastylive, Inc. Neither tastylive nor any of its affiliates are responsible for the products or services provided by tasty Software Solutions, LLC. Cryptocurrency trading is not suitable for all investors due to the number of risks involved. The value of any cryptocurrency, including digital assets pegged to fiat currency, commodities, or any other asset, may go to zero.
© copyright 2013 - 2026 tastylive, Inc. All Rights Reserved. Applicable portions of the Terms of Use on tastylive.com apply. Reproduction, adaptation, distribution, public display, exhibition for profit, or storage in any electronic storage media in whole or in part is prohibited under penalty of law, provided that you may download tastylive’s podcasts as necessary to view for personal use. tastylive was previously known as tastytrade, Inc. tastylive is a trademark/servicemark owned by tastylive, Inc.
Your privacy choices