Micron Earnings Preview: Can the AI Memory Cycle Keep Delivering?

Micron Earnings Preview: Can the AI Memory Cycle Keep Delivering?
By:Mike Butler
- Micron stock has climbed roughly 279% year to date and more than 550% over the past year, pushing its market cap past $1 trillion ahead of Wednesday's fiscal Q4 report.
- Analysts are forecasting Q4 EPS of $31.52 on revenue of $50.6 billion, representing year-over-year earnings growth of approximately 938%, with Micron's own guidance calling for $50 billion in revenue and 86% non-GAAP gross margin.
- Micron has locked in roughly $100 billion in binding, multi-year HBM take-or-pay contracts and 16 strategic customer agreements worth over $22 billion in commitments, shifting the business away from spot pricing toward infrastructure-style revenue visibility.
- Options traders are pricing a post-earnings move of roughly 8.5% to 11%, one of the largest implied moves of any large-cap company reporting this earnings season, with call volume outpacing puts by a wide margin heading into the print.
- The central bear risk is a 2027-2028 oversupply event, as Micron, SK Hynix, and Samsung all ramp massive, simultaneous capital expenditure programs that could eventually flood the market with new HBM and DRAM capacity just as pricing sits at record highs.
Micron Earnings Preview - September 2026
Micron Technology (NASDAQ: MU) reports fiscal fourth-quarter 2026 results after the closing bell on Wednesday, September 30, with a call scheduled for 4:30 p.m. ET. The stock closed around $1,082 on Friday, September 25, against a 52-week range of roughly $154.65 to $1,255.00. Shares are up close to 279% year to date and have gained more than 550% over the trailing 12 months, a run that pushed Micron's market cap above $1 trillion and turned it into one of the defining large-cap stories of the AI trade.
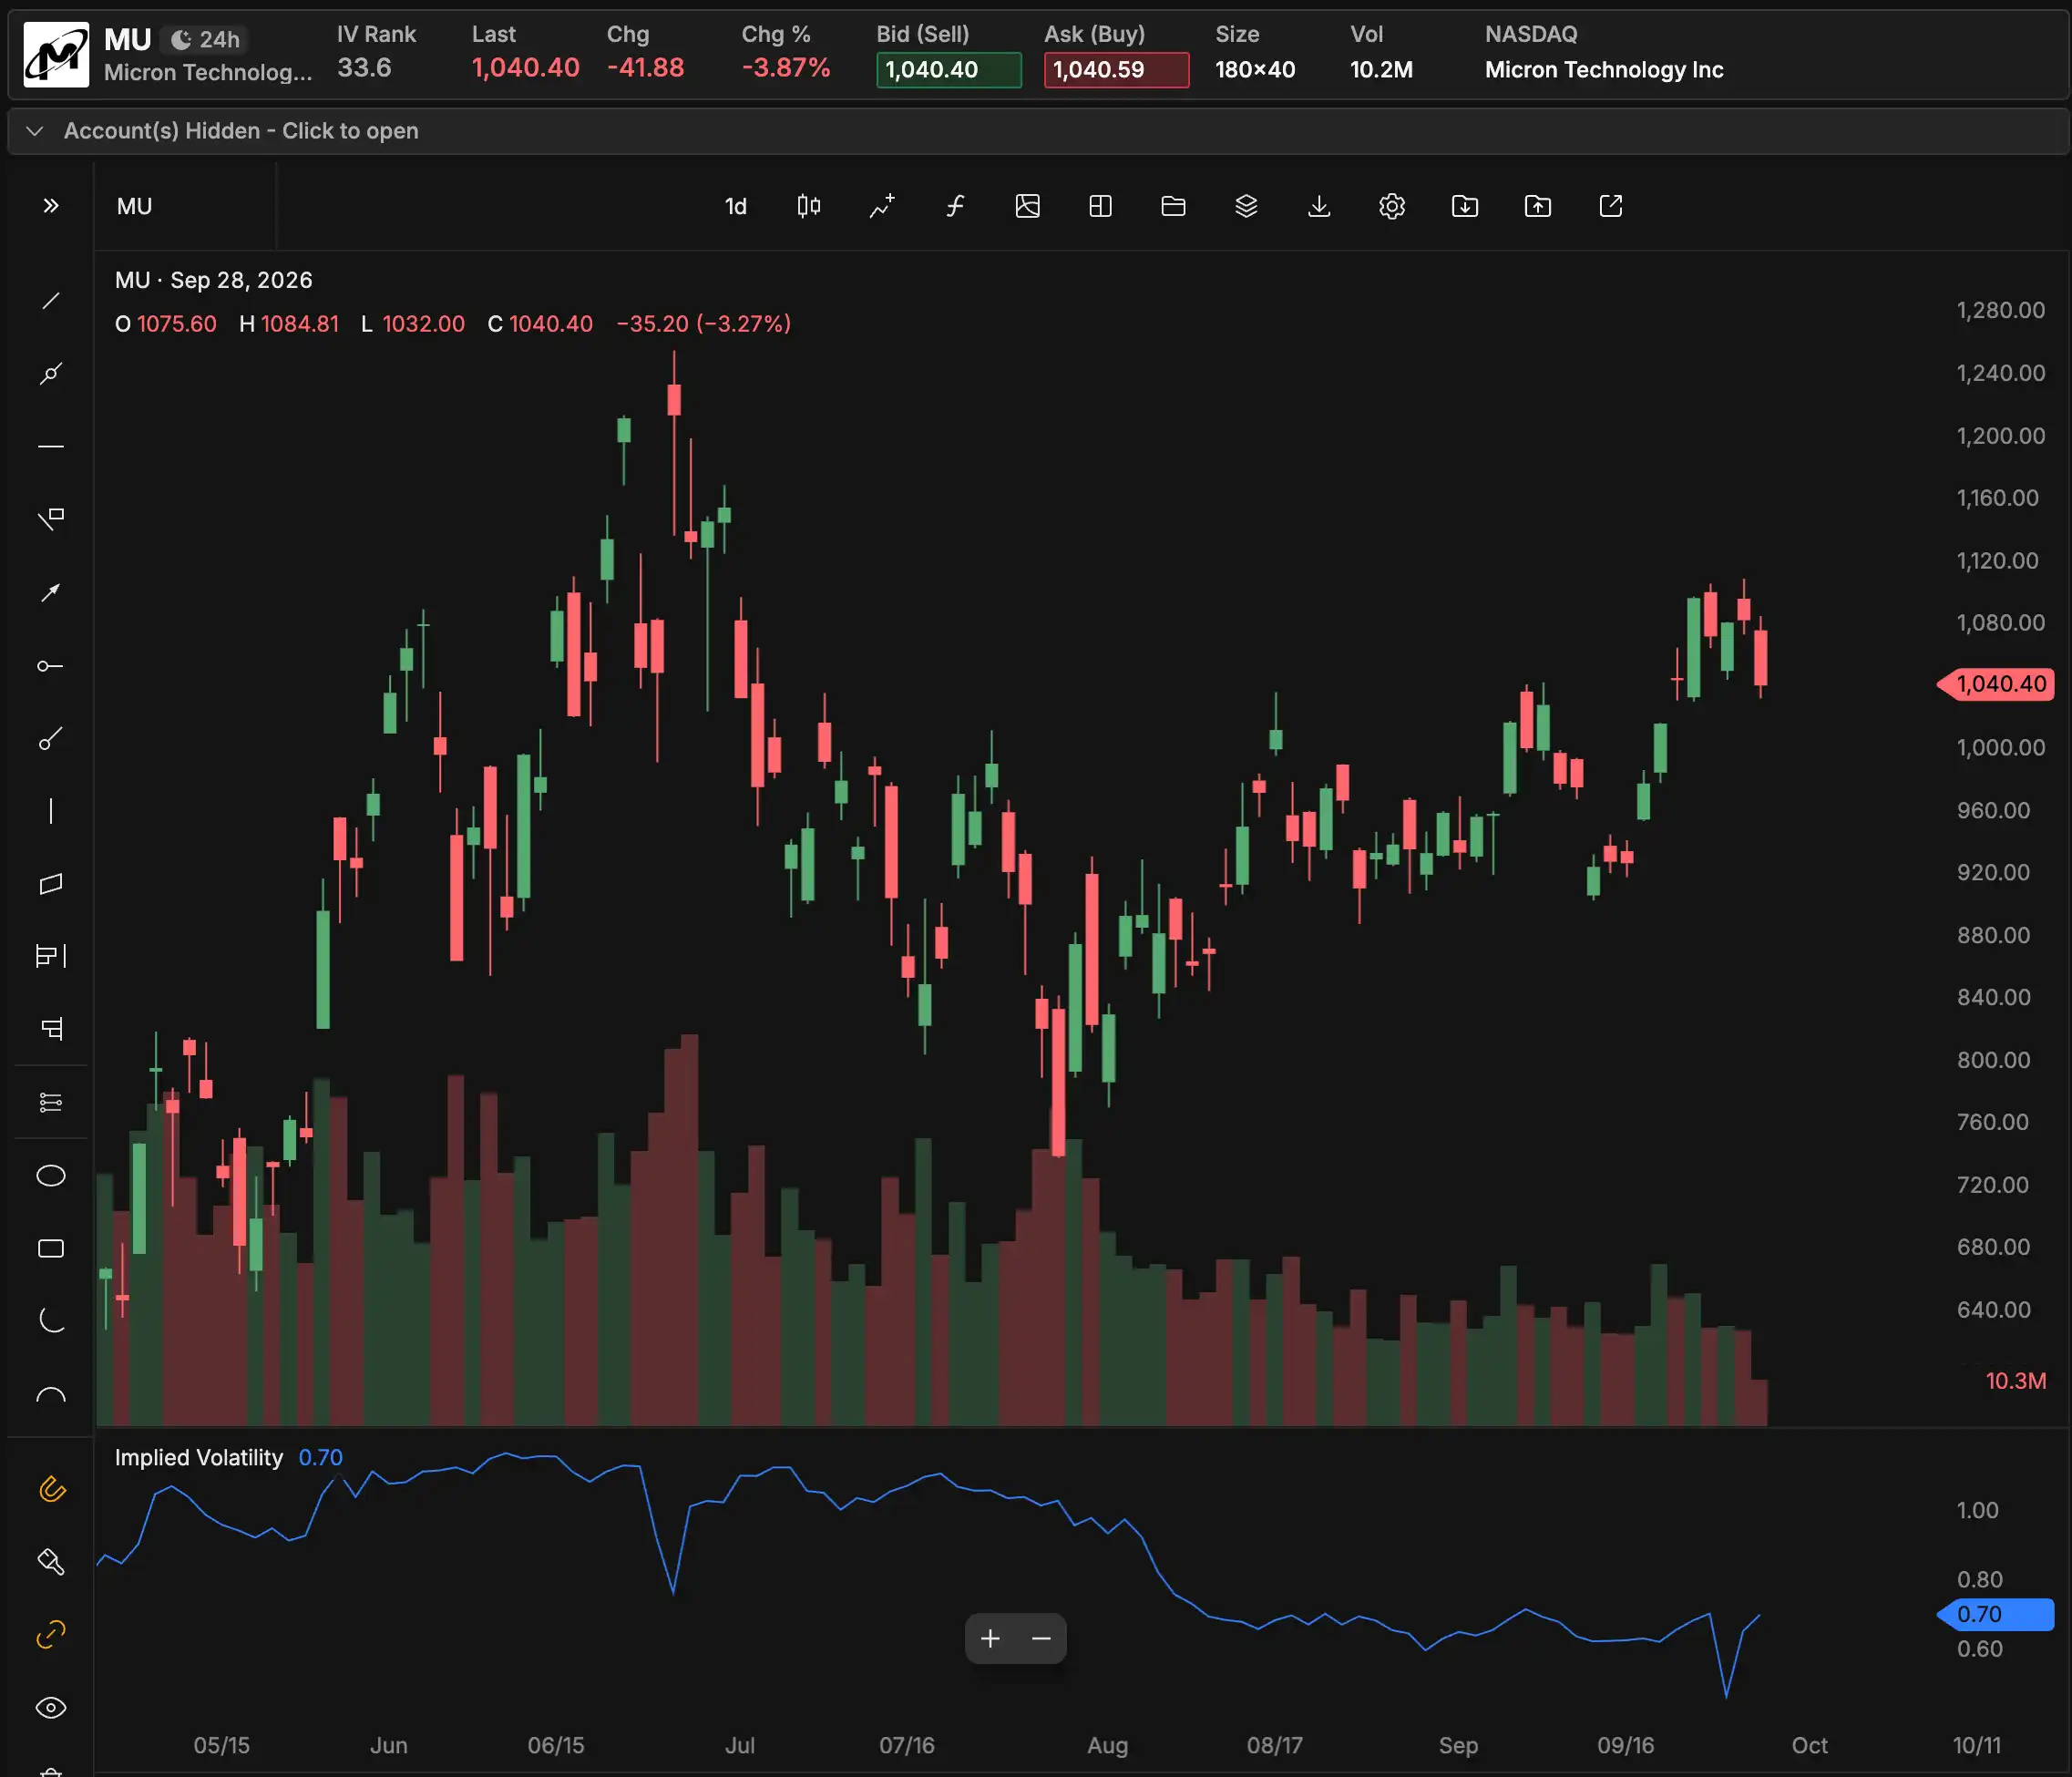
Micron's own guidance, issued alongside its blowout fiscal Q3 report on June 24, called for Q4 revenue of $50 billion (plus or minus $1 billion), non-GAAP EPS of $31.00 (plus or minus $1.00), and non-GAAP gross margin near 86%. Wall Street has since drifted slightly above that midpoint, with the current consensus sitting near $50.6 billion in revenue and $31.52 in EPS, up from $3.03 a year ago. That works out to year-over-year EPS growth of roughly 938%, one of the largest earnings swings of any mega-cap stock this reporting season.
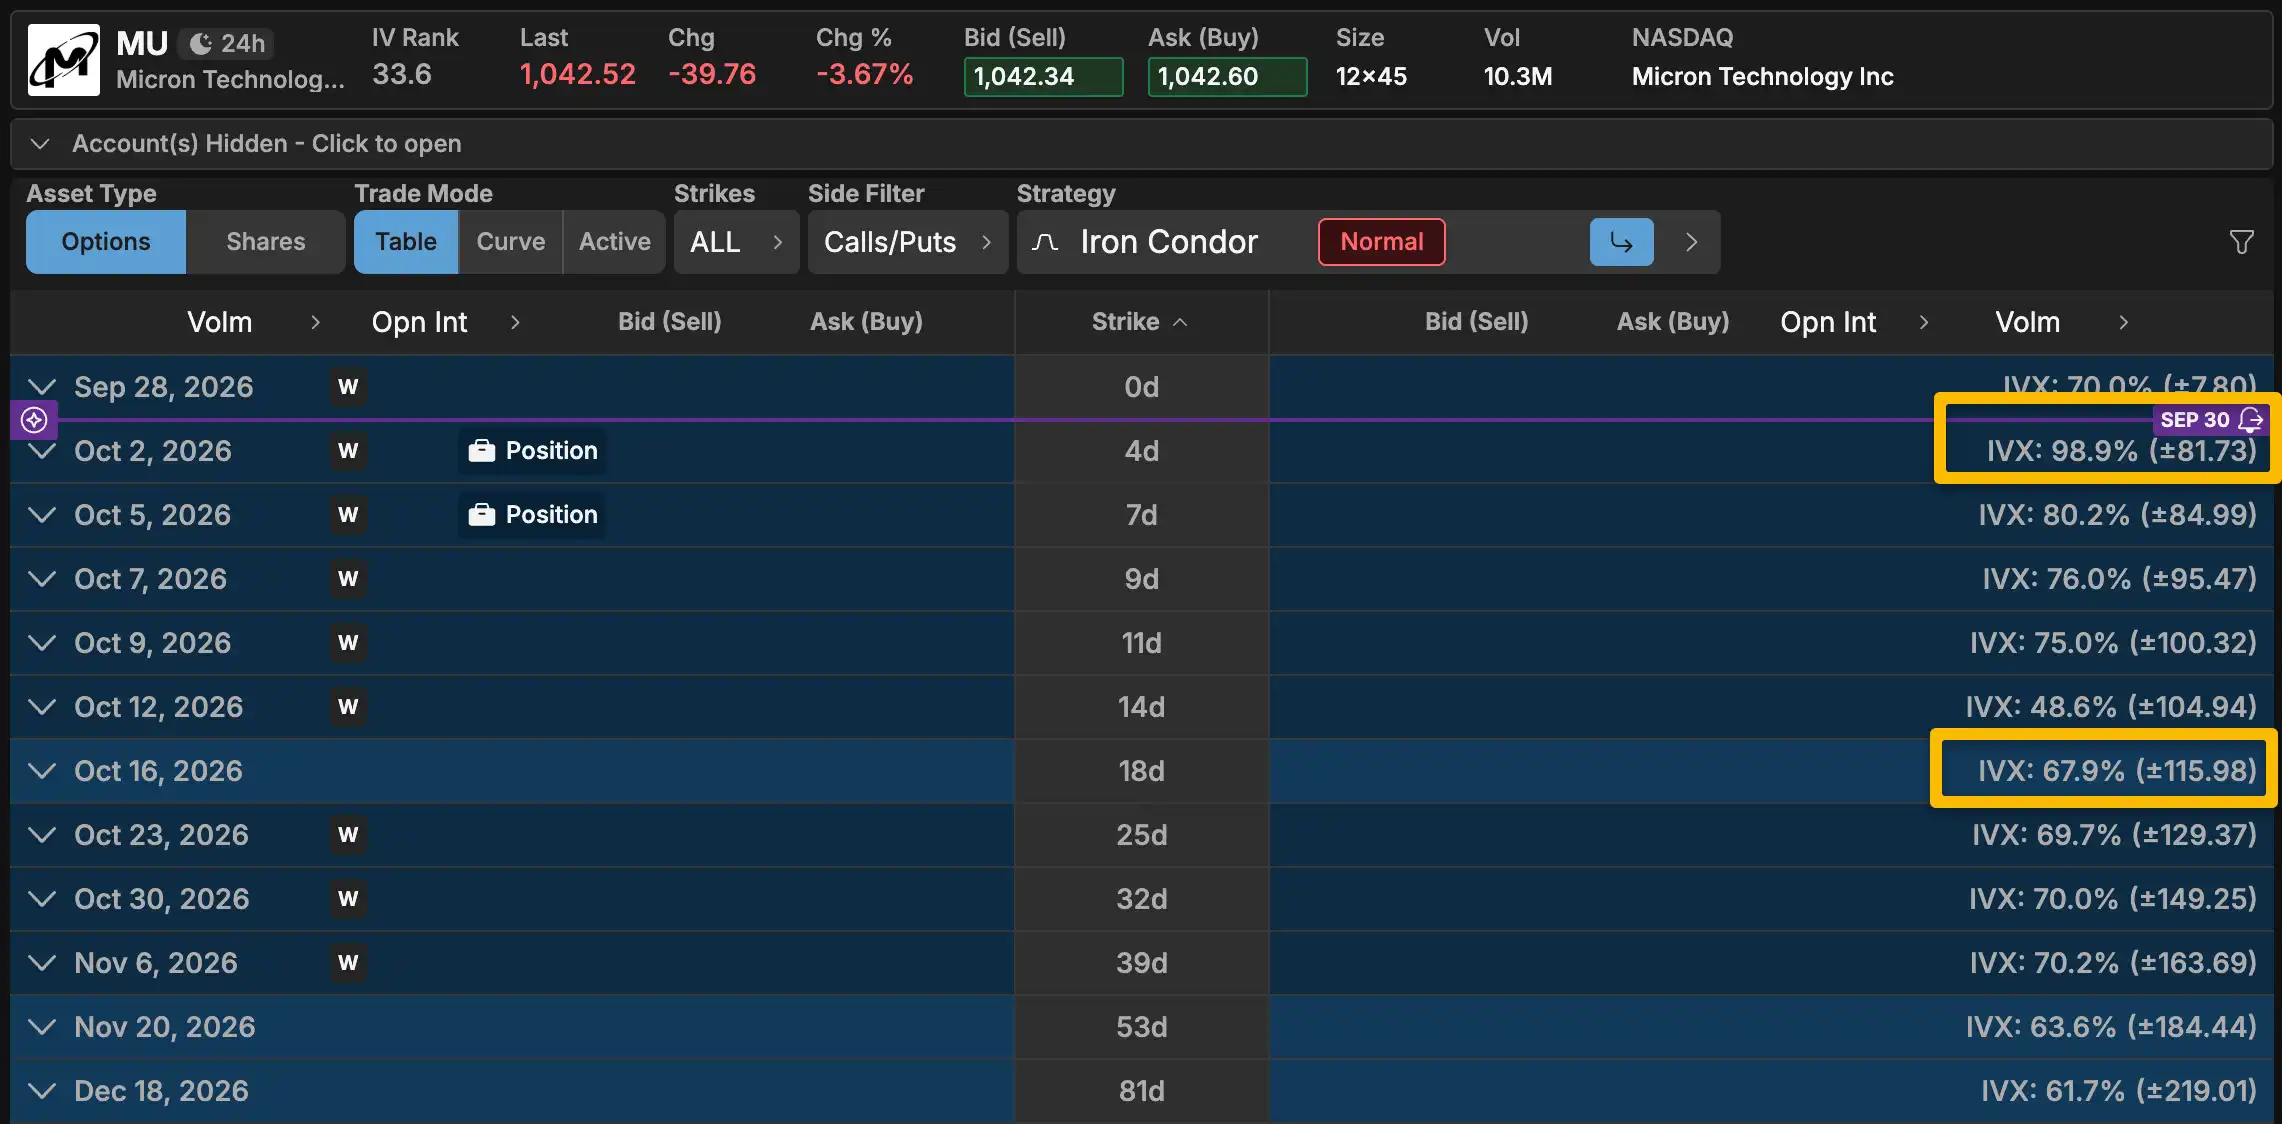
Implied volatility has climbed sharply as the earnings date approached, with the options market pricing a post-earnings move of roughly 8.5% to 11% depending on the source and the day it's measured. Pre-earnings options volume has run well above normal, with calls leading puts by a wide margin, a sign that positioning heading into Wednesday's print skews bullish. With just a +-$116 implied move through the October options cycle, this weeks earnings announcement accounts for a big chunk of that at +-$80 and could result in some fireworks after the announcement.
Why HBM Supply Is Sold Out Through 2027
The core driver behind Micron's rally hasn't changed much since its last report: AI infrastructure needs memory, and there are only three companies on earth that make nearly all of the world's DRAM and NAND. Micron's fiscal Q3 revenue hit a record $41.46 billion, up roughly 345% year over year, powered by high-bandwidth memory shipments tied to Nvidia's AI accelerator ramp. Management said on the Q3 call that HBM capacity was largely booked through calendar 2027 and into 2028, and Micron has since disclosed roughly $100 billion in binding, multi-year HBM take-or-pay contracts alongside 16 strategic customer agreements worth more than $22 billion in cash and cash-equivalent commitments, most running through 2030.
That shift matters because it moves Micron away from the boom-bust, spot-price economics that have defined the memory industry for decades and toward something closer to infrastructure-style, contracted revenue. DRAM spot prices are up roughly 52% since January, and Micron is now shipping HBM4 built on its 1-beta DRAM node in high volume for Nvidia's upcoming Vera Rubin platform, a transition several analysts expect to matter more for fiscal 2027 than for Wednesday's print.
Is the Memory Cycle Structurally Broken, or Just at Its Peak?
Micron's gross margin reached 84.9% in fiscal Q3, nearly triple where it stood two years earlier, with Q4 guidance pointing toward roughly 86% and some analysts modeling even higher. UBS, for one, expects Q4 gross margin near 87.6%, about 160 basis points above the high end of guidance. The question hovering over Wednesday's report is whether that kind of margin represents a permanent structural shift in an industry historically defined by violent cyclicality, or whether it marks the top of the current cycle.
Bulls point to the multi-year contract structure as evidence this time is different. Susquehanna analyst Mehdi Hosseini has modeled fiscal 2027 EPS near $200, well above the roughly $165 Street consensus, while UBS has projected EPS of $212, $277 and $219 for fiscal 2027 through 2029, respectively. Skeptics counter that memory has looked structurally different before, only to see pricing power evaporate once new capacity finally comes online.
Bullish Case for Micron Earnings
The bull case rests on durability rather than a single blowout quarter. Wall Street's average price target sits near $1,500 to $1,560, implying roughly 40% to 44% upside from current levels, and the list of bulls is long: UBS at $1,625, Rosenblatt at $1,500, Wells Fargo at $1,400, Citi at $1,300 (up from $1,150), and BMO Capital at $1,300, all reiterated or raised in the week leading into earnings. Rosenblatt's Kevin Cassidy expects another "beat-and-raise" quarter, additional strategic customer agreements, and sequential DRAM and NAND pricing gains of roughly 10% in the November quarter. Wolfe Research has gone further, arguing Micron could repurchase up to 25% of its market cap through 2027 once buyback restrictions lift in December. Bulls also note the stock's average forward price-to-earnings multiple remains inexpensive relative to its growth rate given how sharply EPS estimates have risen over the past 90 days.
Bearish Case for Micron Earnings
Bears aren't arguing that Micron's current quarter will disappoint. They're questioning how long today's pricing power lasts. Samsung, SK Hynix, and Micron are all running enormous, overlapping capital expenditure programs to add DRAM and HBM capacity, and that synchronized buildout raises the risk of an oversupply event in 2027 or 2028 that could pressure average selling prices and compress margins from what may prove to be a cyclical peak. Goldman Sachs remains the most prominent skeptic on Wall Street, holding a price target near $400 and warning that memory's cyclicality hasn't been repealed, just delayed. Susquehanna has also flagged a potential "teeter-totter" dynamic, where near-term guidance satisfies the market but the real inflection tied to Nvidia's Rubin platform doesn't show up in Micron's numbers until 2027. With the stock priced for a near-flawless quarter and options implying a double-digit move, even modestly cautious language around fiscal Q1 guidance or HBM pricing sustainability could trigger a sharp sell-the-news reaction.
Mike Butler, tastylive director of market intelligence, has been trading the markets for a decade. He appears on the tastylive morning show Monday - Friday. @tradermikeyb
For live daily programming, market news and commentary, visit tastylive or the YouTube channel tastylive (for options traders).
Trade with a better broker, open a tastytrade account today. tastylive, Inc. and tastytrade, Inc. are separate but affiliated companies.
Options involve risk and are not suitable for all investors. Please read Characteristics and Risks of Standardized Options before deciding to invest in options.
tastylive content is created, produced, and provided solely by tastylive, Inc. (“tastylive”) and is for informational and educational purposes only. It is not, nor is it intended to be, trading or investment advice or a recommendation that any security, futures contract, digital asset, other product, transaction, or investment strategy is suitable for any person. Trading securities, futures products, and digital assets involve risk and may result in a loss greater than the original amount invested. tastylive, through its content, financial programming or otherwise, does not provide investment or financial advice or make investment recommendations. Investment information provided may not be appropriate for all investors and is provided without respect to individual investor financial sophistication, financial situation, investing time horizon or risk tolerance. tastylive is not in the business of transacting securities trades, nor does it direct client commodity accounts or give commodity trading advice tailored to any particular client’s situation or investment objectives. Supporting documentation for any claims (including claims made on behalf of options programs), comparisons, statistics, or other technical data, if applicable, will be supplied upon request. tastylive is not a licensed financial adviser, registered investment adviser, or a registered broker-dealer. Options, futures, and futures options are not suitable for all investors. Prior to trading securities, options, futures, or futures options, please read the applicable risk disclosures, including, but not limited to, the Characteristics and Risks of Standardized Options Disclosure and the Futures and Exchange-Traded Options Risk Disclosure found on tastytrade.com/disclosures.
tastytrade, Inc. ("tastytrade”) is a registered broker-dealer and member of FINRA, NFA, and SIPC. tastytrade was previously known as tastyworks, Inc. (“tastyworks”). tastytrade offers self-directed brokerage accounts to its customers. tastytrade does not give financial or trading advice, nor does it make investment recommendations. You alone are responsible for making your investment and trading decisions and for evaluating the merits and risks associated with the use of tastytrade’s systems, services or products. tastytrade is a wholly-owned subsidiary of tastylive, Inc.
tastytrade has entered into a Marketing Agreement with tastylive (“Marketing Agent”) whereby tastytrade pays compensation to Marketing Agent to recommend tastytrade’s brokerage services. The existence of this Marketing Agreement should not be deemed as an endorsement or recommendation of Marketing Agent by tastytrade. tastytrade and Marketing Agent are separate entities with their own products and services. tastylive is the parent company of tastytrade.
tastyfx, LLC (“tastyfx”) is a Commodity Futures Trading Commission (“CFTC”) registered Retail Foreign Exchange Dealer (RFED) and Introducing Broker (IB) and Forex Dealer Member (FDM) of the National Futures Association (“NFA”) (NFA ID 0509630). Leveraged trading in foreign currency or off-exchange products on margin carries significant risk and may not be suitable for all investors. We advise you to carefully consider whether trading is appropriate for you based on your personal circumstances as you may lose more than you invest.
tastycrypto is provided solely by tasty Software Solutions, LLC. tasty Software Solutions, LLC is a separate but affiliate company of tastylive, Inc. Neither tastylive nor any of its affiliates are responsible for the products or services provided by tasty Software Solutions, LLC. Cryptocurrency trading is not suitable for all investors due to the number of risks involved. The value of any cryptocurrency, including digital assets pegged to fiat currency, commodities, or any other asset, may go to zero.
© copyright 2013 - 2026 tastylive, Inc. All Rights Reserved. Applicable portions of the Terms of Use on tastylive.com apply. Reproduction, adaptation, distribution, public display, exhibition for profit, or storage in any electronic storage media in whole or in part is prohibited under penalty of law, provided that you may download tastylive’s podcasts as necessary to view for personal use. tastylive was previously known as tastytrade, Inc. tastylive is a trademark/servicemark owned by tastylive, Inc.
Your privacy choices