Most Markets Are Already Betting on a Slowdown. Are Stocks Next?

Most Markets Are Already Betting on a Slowdown. Are Stocks Next?
By:Ilya Spivak
Bonds are up and gold won’t fall even as oil climbs, while the US dollar seems so weak the euro is holding up despite a crisis in France. If markets fear a slowdown, when will stocks notice?
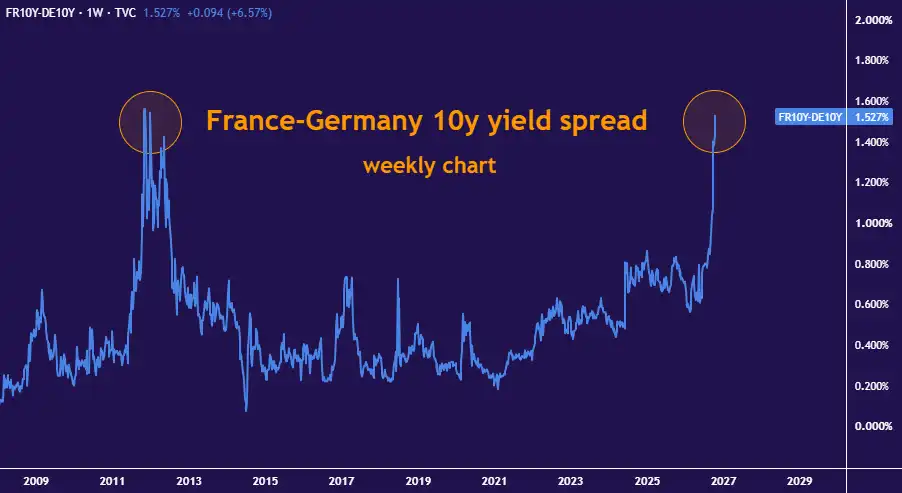
- The euro held firm even as the French-German bond yield spread hit its widest since the 2011 debt crisis
- The Atlanta Fed’s GDPNow model cut its third-quarter growth estimate to 3.5%
- Markets still price 50bps of Fed rate hikes in 2027 that officials don’t expect, leaving room to unwind
Stocks are treading water as major event risk approaches. The S&P 500 is consolidating after last week’s breakdown, and the tech-heavy Nasdaq 100 slipped after failing to reclaim the 30,000 level it broke on the way down. Indecision is perhaps natural with a heavy run of tech earnings ahead.
Other markets are far less quiet. Treasury bonds have rallied since the start of October, pulling yields lower even as crude oil prices climbed. Gold has held its ground despite pricier energy and hot US inflation data. Meanwhile, the US dollar is getting hammered.
The euro won’t fall, and that says a lot about the dollar
Perhaps the most jarring signal comes from the euro. The yield spread between French and German 10-year government bonds has widened to around 153 basis points (bps), the highest since late 2011 at the height of the Eurozone debt crisis and within a few basis points of that episode’s peak (156bps). Germany’s lightly indebted economy serves as the region’s benchmark for safety, while France’s fiscal path looks increasingly unsustainable, so investors are demanding more to lend to Paris.
That kind of stress might be expected to sink the single currency. Yet the euro is refusing to decline against the US dollar, suggesting the greenback is anything but strong. Elsewhere, the British pound and Canadian dollar are rallying, and the Australian dollar is attempting to launch a more lasting advance.
The most plausible explanation for all of this is that markets have moved on from fearing what bubbling inflation and rising rates may do to the economy to pricing the damage they have already done. Traders may be waking up to the possibility that demand destruction amid an economic slowdown could be a more potent disinflationary force than the oil shock is inflationary.
Can the economy keep growing without the consumer?
The Atlanta Fed’s GDPNow model now puts third-quarter growth at 3.5% after its latest downgrade. That would still be a solid quarter, but the direction matters more than the level. Since mid-August, the data feeding the model have mostly carried negative implications the economy.

When official GDP figures arrive October 29, the composition may matter most. The Fed’s Beige Book says the World Cup boost to consumption in the second quarter is gone, with no easy replacement. A return to first-quarter dynamics, when consumers did little of the lifting and business investment tied to the AI buildout drove almost all of the growth, would be a warning sign. Household spending makes up about 68% of the economy, while that investment accounts for roughly 14%. If consumers retrench in earnest, the data center boom almost certainly cannot fill the gap.
Rate hike bets have yet to reflect those worries. Fed funds futures put the odds of a hold at next week’s policy meeting at nearly 83% and see a 25bps hike in December as almost certain, in line with the Fed’s September projections. For 2027, markets price hikes by March and June, while officials see rates peaking this year. That leaves traders 50bps more hawkish than the Fed.
October’s preliminary purchasing managers index (PMI) data from S&P Global arrive Thursday and Friday. Those surveys have been very strong recently. Any unexpected softening now would reinforce the story other markets seem to be telling.
If traders start peeling rate hikes off the board for 2027 and moving closer to the Fed’s view, the dollar’s slide may extend, gold could bounce, and bonds may rally further. Stocks may not welcome that, however. Rate hikes canceled because of a cyclical growth risk are hardly a reason for comfort.
Ilya Spivak, tastylive Head of Global Macro, has over 15 years of experience in trading strategy. He specializes in identifying thematic moves in currencies, commodities, interest rates and equities. He hosts Macro Money and co-hosts Overtime, Monday-Thursday. @Ilyaspivak
For live daily programming, market news and commentary, visit tastylive.com or @tastyliveshow on YouTube
Trade with a better broker, open a tastytrade account today. tastylive, Inc. and tastytrade, Inc. are separate but affiliated companies.
Options involve risk and are not suitable for all investors. Please read Characteristics and Risks of Standardized Options before deciding to invest in options.
tastylive content is created, produced, and provided solely by tastylive, Inc. (“tastylive”) and is for informational and educational purposes only. It is not, nor is it intended to be, trading or investment advice or a recommendation that any security, futures contract, digital asset, other product, transaction, or investment strategy is suitable for any person. Trading securities, futures products, and digital assets involve risk and may result in a loss greater than the original amount invested. tastylive, through its content, financial programming or otherwise, does not provide investment or financial advice or make investment recommendations. Investment information provided may not be appropriate for all investors and is provided without respect to individual investor financial sophistication, financial situation, investing time horizon or risk tolerance. tastylive is not in the business of transacting securities trades, nor does it direct client commodity accounts or give commodity trading advice tailored to any particular client’s situation or investment objectives. Supporting documentation for any claims (including claims made on behalf of options programs), comparisons, statistics, or other technical data, if applicable, will be supplied upon request. tastylive is not a licensed financial adviser, registered investment adviser, or a registered broker-dealer. Options, futures, and futures options are not suitable for all investors. Prior to trading securities, options, futures, or futures options, please read the applicable risk disclosures, including, but not limited to, the Characteristics and Risks of Standardized Options Disclosure and the Futures and Exchange-Traded Options Risk Disclosure found on tastytrade.com/disclosures.
tastytrade, Inc. ("tastytrade”) is a registered broker-dealer and member of FINRA, NFA, and SIPC. tastytrade was previously known as tastyworks, Inc. (“tastyworks”). tastytrade offers self-directed brokerage accounts to its customers. tastytrade does not give financial or trading advice, nor does it make investment recommendations. You alone are responsible for making your investment and trading decisions and for evaluating the merits and risks associated with the use of tastytrade’s systems, services or products. tastytrade is a wholly-owned subsidiary of tastylive, Inc.
tastytrade has entered into a Marketing Agreement with tastylive (“Marketing Agent”) whereby tastytrade pays compensation to Marketing Agent to recommend tastytrade’s brokerage services. The existence of this Marketing Agreement should not be deemed as an endorsement or recommendation of Marketing Agent by tastytrade. tastytrade and Marketing Agent are separate entities with their own products and services. tastylive is the parent company of tastytrade.
tastyfx, LLC (“tastyfx”) is a Commodity Futures Trading Commission (“CFTC”) registered Retail Foreign Exchange Dealer (RFED) and Introducing Broker (IB) and Forex Dealer Member (FDM) of the National Futures Association (“NFA”) (NFA ID 0509630). Leveraged trading in foreign currency or off-exchange products on margin carries significant risk and may not be suitable for all investors. We advise you to carefully consider whether trading is appropriate for you based on your personal circumstances as you may lose more than you invest.
tastycrypto is provided solely by tasty Software Solutions, LLC. tasty Software Solutions, LLC is a separate but affiliate company of tastylive, Inc. Neither tastylive nor any of its affiliates are responsible for the products or services provided by tasty Software Solutions, LLC. Cryptocurrency trading is not suitable for all investors due to the number of risks involved. The value of any cryptocurrency, including digital assets pegged to fiat currency, commodities, or any other asset, may go to zero.
© copyright 2013 - 2026 tastylive, Inc. All Rights Reserved. Applicable portions of the Terms of Use on tastylive.com apply. Reproduction, adaptation, distribution, public display, exhibition for profit, or storage in any electronic storage media in whole or in part is prohibited under penalty of law, provided that you may download tastylive’s podcasts as necessary to view for personal use. tastylive was previously known as tastytrade, Inc. tastylive is a trademark/servicemark owned by tastylive, Inc.
Your privacy choices