Qualcomm Earnings Preview: Can AI Data Centers Offset the Apple Cliff?

Qualcomm Earnings Preview: Can AI Data Centers Offset the Apple Cliff?
By:Mike Butler
By: Mike Butler | Nov 2, 2026
- Qualcomm reports fiscal Q4 2026 earnings Wednesday, November 4 after the close. Analysts expect EPS of about $2.16 on revenue of $10.14 billion, which would be down roughly 28% and 10% from the year-ago quarter.
- QCOM stock sits near $165, about 36% below its 52-week high of $259.92, with a market cap near $177 billion and a trailing P/E around 19, a steep discount to most of the chip sector.
- Handset revenue fell 20% to $5.09 billion last quarter as rising memory costs hit smartphone demand and Apple shifts toward its own modems, while automotive revenue jumped 61% to $1.59 billion.
- The real catalyst is fiscal 2027 guidance. Management has said non-handset growth should accelerate to more than 60% next year from 24% in fiscal 2026, and that most chip sales will come from outside smartphones.
- Options are pricing in a move of roughly 8.6%, versus a 10-year average earnings move of about 7.5%, and the stock slipped 2.6% after the last report despite a revenue beat.
Qualcomm Earnings Preview - November 2026
Qualcomm (NASDAQ: QCOM) heads into its fiscal Q4 report as one of the most debated names in semiconductors. While AI-linked peers like AMD pushed toward $1 trillion valuations this year, QCOM has traded the other way. Shares sit near $165 against a 52-week range of $121.99 to $259.92, and the stock carries a forward dividend of $3.68, or a yield of about 2.2%. Wall Street’s average rating is Hold, with 11 Buy ratings, 23 Holds and 3 Sells among 37 analysts, and the average price target of roughly $196 implies about 19% upside.
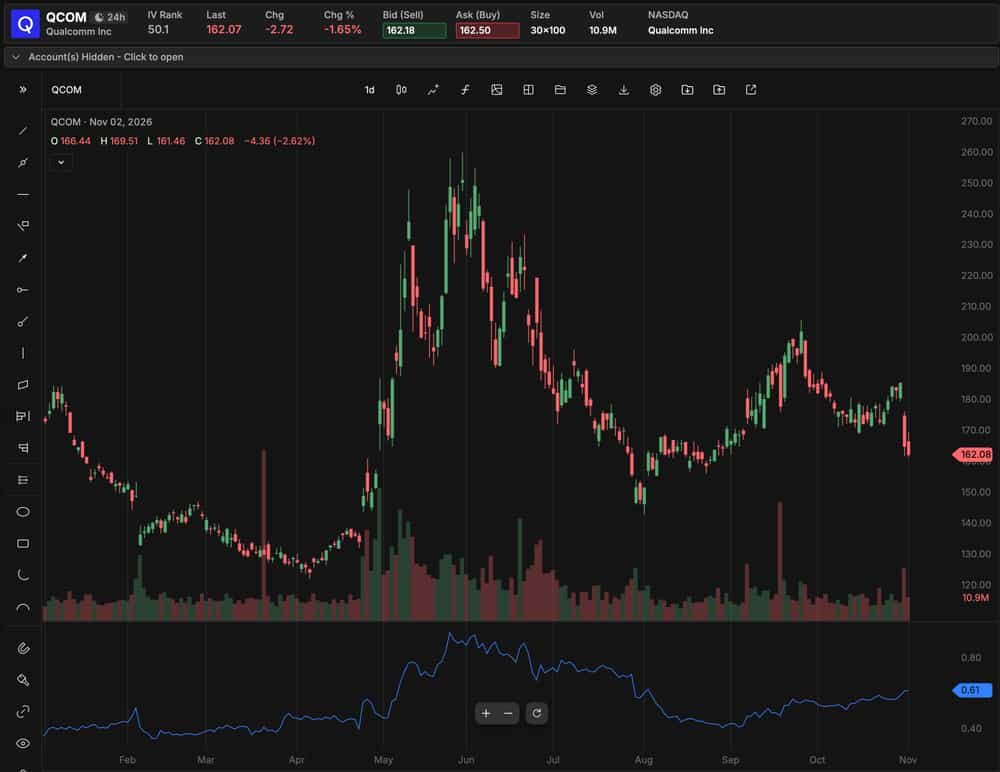
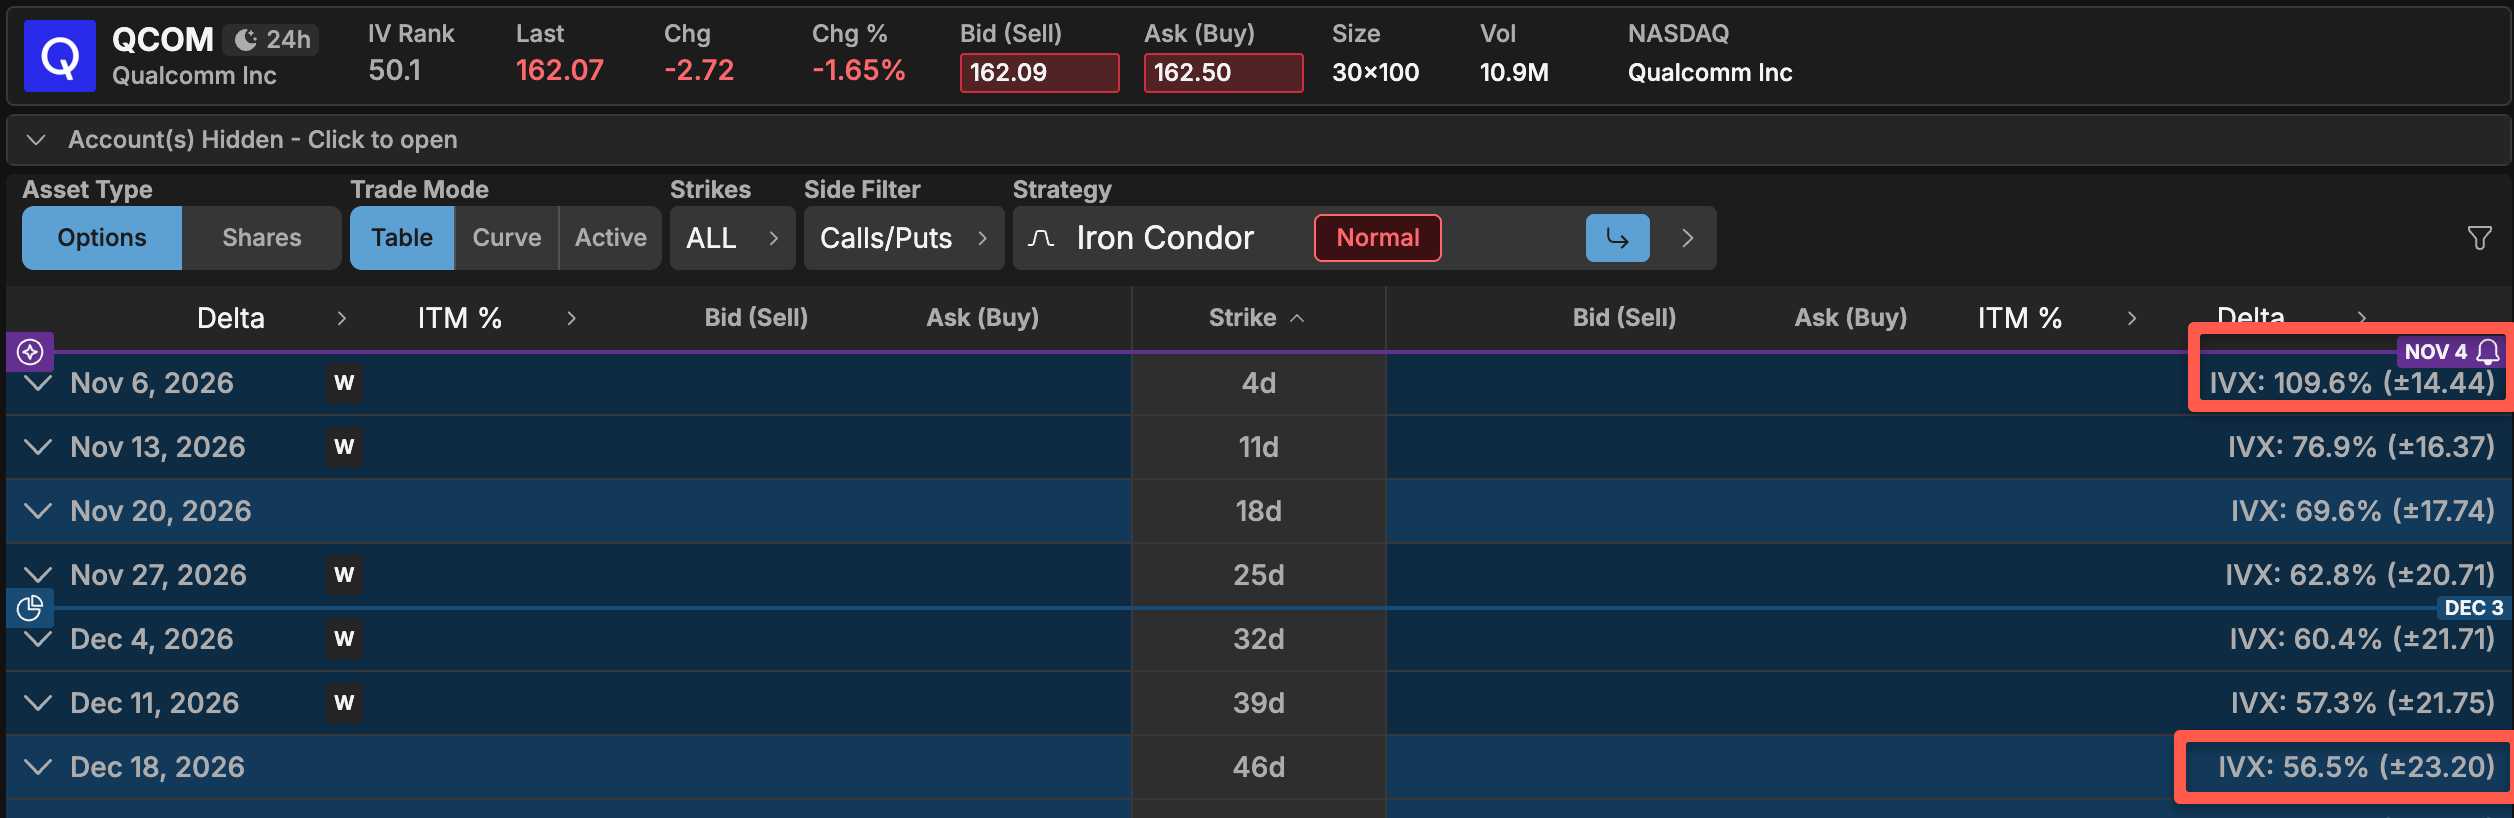
Implied volatility has risen into the print. Data providers show an expected move around 8.6% for Thursday’s session, which works out to roughly $14 on a stock near $165. For context, QCOM has averaged an earnings-day move of about 6.7% over the last 12 reports and about 7.5% over the past decade. Last quarter, options priced in a move of roughly 8% to 9%, and the stock closed down 2.6% after Qualcomm guided profit below estimates and warned that Apple revenue would shrink faster than expected. QCOM has a very high implied volatility ratio for this week's earnings compared to December 2026 - this week's expected move of +-$14 accounts for 60% of the December implied range of +-$23, telling us the market is putting a heavy weight on this week's earnings announcement.
What Wall Street Expects From Qualcomm in Q4
The setup here is a “transition quarter.” Qualcomm guided fiscal Q4 revenue to $9.7 billion to $10.5 billion and non-GAAP EPS of $2.05 to $2.25. Consensus sits almost exactly at the midpoint, with revenue near $10.14 billion and EPS between $2.16 and $2.17. A year ago, Qualcomm reported $11.27 billion in revenue and $3.00 in EPS, so the comparison is tough. Looking at the full year, analysts model fiscal 2026 EPS of $7.71, down about 23% from $10.07 in fiscal 2025, with another 7% decline to $7.17 expected in fiscal 2027.
Last quarter set the tone. Q3 revenue came in at $9.95 billion, down 4% year over year, and non-GAAP EPS of $2.21 narrowly missed the $2.23 consensus. CEO Cristiano Amon cited “unprecedented memory prices” along with higher wafer, packaging and testing costs. Qualcomm plans to pass those costs on through double-digit price increases, but investors want to see whether the pricing sticks without hurting demand.
Qualcomm’s Apple Problem and the Handset Slowdown
The largest overhang is Apple. Qualcomm now expects its modem share in the upcoming iPhone to land materially below its earlier 20% estimate, meaning Apple-related revenue is stepping down faster than planned. Reports point to Apple targeting a full replacement of Qualcomm modems as early as 2027, although Apple’s in-house efforts have slipped before.
Memory is the second headwind. Soaring DRAM and NAND prices, driven largely by AI infrastructure demand, are pushing up smartphone bill of materials costs and weighing on consumer electronics sales. Qualcomm responded in October with a global “performance-focused” workforce reduction, with notifications set to begin in November. It booked $70 million of restructuring charges in fiscal Q3, and traders will listen closely for any update on the savings.
Can Data Center and Automotive Fill the Gap?
Qualcomm’s answer to the handset slowdown is diversification. Automotive revenue grew 61% last quarter to $1.59 billion, and management expects another record quarter with growth of around 60% year over year. In IoT, the industrial, networking and robotics category is growing at double digits, with a design win pipeline above $7 billion.
The bigger swing factor is data center. Qualcomm unveiled its AI200 and AI250 inference accelerators in October 2025, with commercial windows in 2026 and 2027, and it has said its first custom-silicon deliveries to a hyperscaler are due in December 2026. The Alphawave acquisition is meant to accelerate that push. Still, analysts at TD Cowen have cautioned that early data center programs carry lower margins, and some of the marquee roadmap chips are not expected until 2028. That timing gap is the heart of the debate.
Bullish Case for Qualcomm Earnings
The bull case rests on low expectations and valuation. QCOM trades near 14 times forward earnings, compared with roughly 17 times for Nvidia and 44 times for Intel as of late July, and the stock is already down more than a third from its high. With consensus sitting right at the middle of guidance, a modest beat paired with a confident fiscal 2027 outlook could shift the narrative quickly. Management has said non-handset growth should exceed 60% in fiscal 2027 and more than offset lost Apple revenue, and bulls will look for any detail on data center customer wins, deployment timing and margins to back that up.
Sentiment is also stretched to the downside. Estimates have been cut repeatedly, several analysts have lowered price targets in recent weeks, and QCOM pays a roughly 2.2% dividend while investors wait. The high end of Wall Street targets reaches $400. If automotive keeps growing near 60% and the company shows early traction in data center, bulls argue the stock is priced as if the diversification story will fail.
Bearish Case for Qualcomm Earnings
Bears argue that the earnings decline is structural, not cyclical. Revenue is expected to fall about 10% and EPS about 28% this quarter, and fiscal 2027 estimates point to a further drop in earnings before any recovery. Apple is moving to in-house modems, memory costs are squeezing both Qualcomm’s margins and its customers’ demand, and handset revenue is already down 20% year over year. Layoffs may help costs, but they also reinforce the idea that the core business is under pressure.
The data center pivot adds execution risk. Bears note that the marquee chips are years away, early programs carry lower margins, and Qualcomm is entering a market dominated by Nvidia and increasingly contested by AMD and custom silicon from the hyperscalers themselves. The last report is a warning too. QCOM nudged past revenue estimates, missed EPS by a couple of cents, and still sold off. Barclays holds an Underweight rating, the lowest price target on the Street is $100, and with Q4 guidance already known, any soft fiscal 2027 outlook could pressure the stock further.
Mike Butler, tastylive director of market intelligence, has been trading the markets for a decade. He appears on the tastylive morning show Monday - Friday. @tradermikeyb
For live daily programming, market news and commentary, visit tastylive or the YouTube Channel tastylive (for options traders).
Trade with a better broker, open a tastytrade account today. tastylive, Inc. and tastytrade, Inc. are separate but affiliated companies.
Options involve risk and are not suitable for all investors. Please read Characteristics and Risks of Standardized Options before deciding to invest in options.
tastylive content is created, produced, and provided solely by tastylive, Inc. (“tastylive”) and is for informational and educational purposes only. It is not, nor is it intended to be, trading or investment advice or a recommendation that any security, futures contract, digital asset, other product, transaction, or investment strategy is suitable for any person. Trading securities, futures products, and digital assets involve risk and may result in a loss greater than the original amount invested. tastylive, through its content, financial programming or otherwise, does not provide investment or financial advice or make investment recommendations. Investment information provided may not be appropriate for all investors and is provided without respect to individual investor financial sophistication, financial situation, investing time horizon or risk tolerance. tastylive is not in the business of transacting securities trades, nor does it direct client commodity accounts or give commodity trading advice tailored to any particular client’s situation or investment objectives. Supporting documentation for any claims (including claims made on behalf of options programs), comparisons, statistics, or other technical data, if applicable, will be supplied upon request. tastylive is not a licensed financial adviser, registered investment adviser, or a registered broker-dealer. Options, futures, and futures options are not suitable for all investors. Prior to trading securities, options, futures, or futures options, please read the applicable risk disclosures, including, but not limited to, the Characteristics and Risks of Standardized Options Disclosure and the Futures and Exchange-Traded Options Risk Disclosure found on tastytrade.com/disclosures.
tastytrade, Inc. ("tastytrade”) is a registered broker-dealer and member of FINRA, NFA, and SIPC. tastytrade was previously known as tastyworks, Inc. (“tastyworks”). tastytrade offers self-directed brokerage accounts to its customers. tastytrade does not give financial or trading advice, nor does it make investment recommendations. You alone are responsible for making your investment and trading decisions and for evaluating the merits and risks associated with the use of tastytrade’s systems, services or products. tastytrade is a wholly-owned subsidiary of tastylive, Inc.
tastytrade has entered into a Marketing Agreement with tastylive (“Marketing Agent”) whereby tastytrade pays compensation to Marketing Agent to recommend tastytrade’s brokerage services. The existence of this Marketing Agreement should not be deemed as an endorsement or recommendation of Marketing Agent by tastytrade. tastytrade and Marketing Agent are separate entities with their own products and services. tastylive is the parent company of tastytrade.
tastyfx, LLC (“tastyfx”) is a Commodity Futures Trading Commission (“CFTC”) registered Retail Foreign Exchange Dealer (RFED) and Introducing Broker (IB) and Forex Dealer Member (FDM) of the National Futures Association (“NFA”) (NFA ID 0509630). Leveraged trading in foreign currency or off-exchange products on margin carries significant risk and may not be suitable for all investors. We advise you to carefully consider whether trading is appropriate for you based on your personal circumstances as you may lose more than you invest.
tastycrypto is provided solely by tasty Software Solutions, LLC. tasty Software Solutions, LLC is a separate but affiliate company of tastylive, Inc. Neither tastylive nor any of its affiliates are responsible for the products or services provided by tasty Software Solutions, LLC. Cryptocurrency trading is not suitable for all investors due to the number of risks involved. The value of any cryptocurrency, including digital assets pegged to fiat currency, commodities, or any other asset, may go to zero.
© copyright 2013 - 2026 tastylive, Inc. All Rights Reserved. Applicable portions of the Terms of Use on tastylive.com apply. Reproduction, adaptation, distribution, public display, exhibition for profit, or storage in any electronic storage media in whole or in part is prohibited under penalty of law, provided that you may download tastylive’s podcasts as necessary to view for personal use. tastylive was previously known as tastytrade, Inc. tastylive is a trademark/servicemark owned by tastylive, Inc.
Your privacy choices